- Follow On:
- [email protected]
- +918655715397
- Thane west, Maharashtra - 400604

Effective inventory management and regular stock audits are essential for maintaining accurate inventory records, controlling costs, reducing losses, and improving operational efficiency. While inventory management focuses on planning, tracking, storing, and controlling stock, inventory audits verify whether physical inventory and recorded data match.
This guide explains the key principles of inventory management, common inventory systems, stock control challenges, inventory audit types, audit procedures, checklists, reporting practices, and best practices businesses can use to improve inventory accuracy and control.
This guide provides a detailed framework covering:
What an inventory audit is
Why it matters
Pre-audit preparation checklist
Step-by-step audit process
Roles and responsibilities
Best practices & tools
Reporting and actionable insights
Before conducting a stock audit, businesses should ensure that inventory records, stock movement data, storage locations, and supporting documentation are properly organized.
Need a more detailed version?
Get a practical inventory audit checklist to help your team prepare, count, reconcile and review inventory more systematically.
[Download Inventory Audit Checklist]
Inventory management is the process of planning, purchasing, receiving, storing, tracking, and controlling inventory throughout its lifecycle. It helps businesses maintain the right stock levels while reducing excess inventory, stockouts, damage, and carrying costs.
Effective inventory management connects purchasing, warehousing, sales, production, and finance data so businesses can maintain accurate stock records and make informed decisions. Regular inventory audits complement this process by verifying whether recorded inventory matches physical stock.
Inventory management requirements vary by business size. Smaller businesses may rely on simpler stock registers and periodic counts, while larger organizations often require ERP systems, automated tracking, barcode or RFID technology, cycle counting, and structured inventory controls.
It ensures:
Accuracy – stock data in the system matches actual physical items.
Loss Prevention – theft, misplacement, or damage is identified early.
Financial Compliance – correct stock valuation for balance sheets, tax, and statutory reporting.
Better Decision-Making – accurate data improves demand forecasting, purchasing, and operational planning.
Businesses use different inventory management approaches depending on their inventory volume, operating model, product type, and technology infrastructure.
A perpetual inventory system continuously updates inventory records as purchases, sales, returns, and stock movements occur. It provides businesses with near real-time visibility into inventory levels.
A periodic system updates inventory records at defined intervals through physical stock counts. It can be suitable for smaller businesses with lower inventory volumes but provides less frequent visibility.
ABC analysis categorizes inventory according to value or business importance. High-value or critical items receive greater monitoring and control, while lower-value items may require simpler controls.
Just-in-Time inventory aims to maintain stock close to actual demand by coordinating purchasing and production with operational requirements. This can reduce holding costs but requires reliable suppliers and accurate demand planning.
FIFO means First-In, First-Out, where older inventory is generally issued before newer inventory. LIFO means Last-In, First-Out, where newer inventory is issued first. The appropriate accounting treatment depends on applicable accounting requirements and business circumstances.
Inventory management software, barcode systems, RFID, ERP platforms, and automated tracking tools can help businesses monitor stock movement, improve record accuracy, and generate inventory reports.
Different businesses use different audit methods depending on their size, stock complexity, industry regulations, and internal control needs. The four most common audit types are:
A comprehensive physical verification of all inventory items in a warehouse, store, or production facility. Every item is counted, inspected, and reconciled with system records.
Instead of auditing all stock at once, cycle counting audits a subset of inventory on a rotational basis (daily, weekly, or monthly). Over time, all items are audited without disrupting operations.
A random, unannounced check of selected inventory items to verify accuracy and detect irregularities such as theft, misplacement, or fraud.
An external auditor or consulting firm is engaged to verify inventory for compliance, financial accuracy, or certification purposes.
Inventory audits are crucial for ensuring that stock records match reality, reducing errors that impact finances and operations. They help prevent losses from theft, damage, or misplacement while maintaining compliance with tax and regulatory requirements. Regular audits improve cash flow management, support smarter purchasing decisions, and enhance overall business efficiency. In short, they safeguard profitability and build trust with stakeholders.
Financial Accuracy: Prevents misstated balance sheets and profit margins.
Loss Prevention: Detects theft, spoilage, damage, and shrinkage.
Operational Efficiency: Optimizes purchasing, storage, and cash flow.
Regulatory Compliance: Ensures adherence to tax, GST, and statutory requirements.
Decision-Making: Provides data for demand forecasting and business strategy.
A successful inventory audit begins long before you start counting items. It requires structured planning, a reliable checklist, and a team that understands the objective. Whether you’re preparing for an internal review or a third-party audit, having a system in place makes all the difference.
Here’s a detailed pre-audit checklist:
Ensure your ERP, POS, or Excel sheets reflect the latest transactions (purchases, sales, transfers).
Reconcile recent shipments and returns before starting.
Close pending stock entries to prevent mismatches.
Gather barcode scanners, RFID devices, tablets, or mobile audit apps.
Ensure tools are tested, charged, and connected to your system.
Keep backup tally sheets in case of device failure.
Organize stock by category, batch, expiry, or storage zone.
Clearly label shelves, bins, and pallets to speed up counting.
Separate quarantined, damaged, or obsolete items before the audit.
Decide whether to use internal staff or external auditors.
Train team members on counting methods, tools, and audit templates.
Assign roles: counters, verifiers, recorders, and supervisors.
Use Excel, Google Sheets, or inventory software templates for consistency.
Pre-define fields like SKU, batch, location, quantity, condition, notes.
Standardization prevents data entry errors and eases reconciliation.
Announce the audit schedule well in advance.
Freeze stock movement (inbound/outbound) during counting.
Document the baseline inventory status before freezing.
Keep purchase orders, invoices, GRNs (Goods Receipt Notes), and dispatch slips accessible.
Ensure stock policies (valuation, write-offs, damaged stock handling) are documented.
Confirm audit scope complies with company policies and regulatory requirements.
An inventory audit typically involves seven key steps: planning the audit, reviewing inventory records, verifying physical stock, reconciling discrepancies, investigating variances, reporting findings and implementing corrective actions.
Define the audit scope, locations, inventory categories, responsible team and audit date.
Check inventory reports, SKU records, purchase records, sales records, transfers and previous audit findings.
Count physical inventory and compare quantities with the inventory management system or stock records.
Identify differences between physical quantities and recorded quantities and document the variance.
Review possible causes such as receiving errors, incorrect entries, transfers, returns, damaged goods or unrecorded stock movements.
Document inventory quantities, discrepancies, causes, adjustments and significant findings.
Address recurring inventory issues and establish controls to reduce future discrepancies.
An inventory audit is more than just a compliance activity — it’s a strategic tool that improves accuracy, reduces losses, and drives operational efficiency. Understanding its objectives and the people responsible for executing the audit is key to making the most of the process.
The main goal of an inventory audit is to verify that the physical stock matches the recorded data. But beyond this basic purpose, there are several deeper objectives:
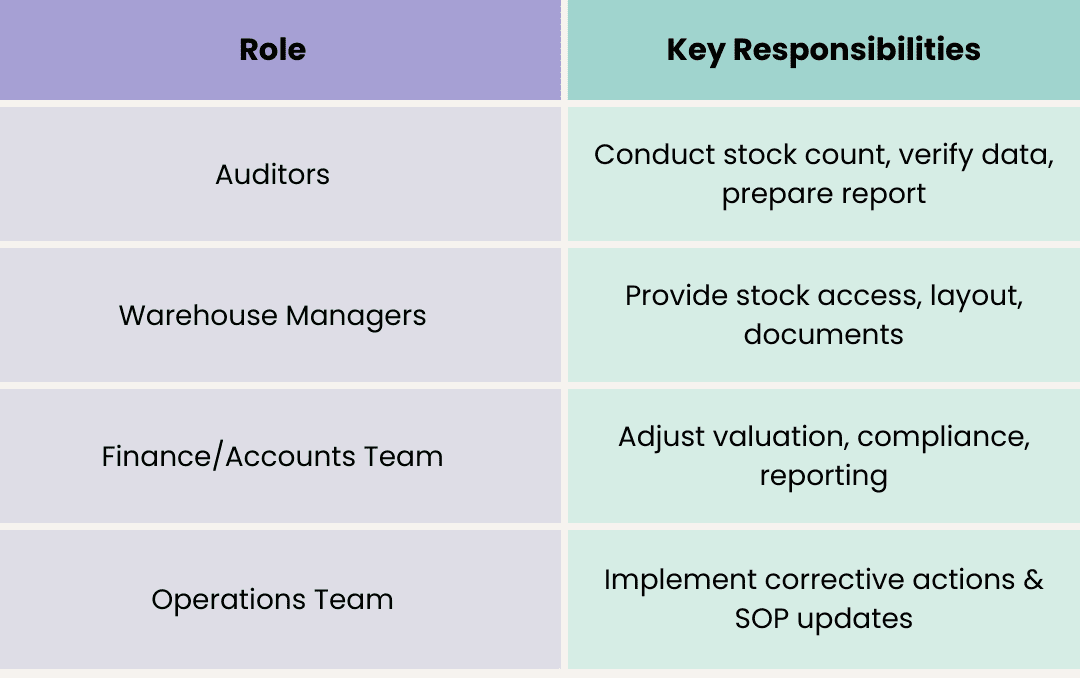
An audit requires coordination between departments. Here are the typical duties and responsibilities:
To ensure consistent and effective audits over time, businesses should follow these proven practices:
Once the inventory audit is completed, the final and most critical step is reporting. A well-documented inventory audit report not only communicates findings but also drives improvements in internal controls and operations.
An audit report typically summarizes:
Pro Tip: Keep your report easy to interpret with charts, tables, and checklists. If you’re working with external auditors, they may also attach a formal opinion letter or certification.
Example: Inventory Audit in Action
Let’s say a retail company conducted a quarterly audit and found the following:
The final report recommended real-time stock tracking, markdowns on outdated items, and periodic cycle counts. As a result, the company reduced waste by 12% in the next quarter and optimized storage.
This illustrates how small changes, backed by data, can lead to measurable outcomes.
Technology can significantly reduce the time and effort needed to carry out a comprehensive inventory audit. Here are some effective tools:
Choosing the right tools depends on the size of your operations, budget, and integration needs.
A stock or inventory audit may sound like a back-end function, but in reality, it’s a frontline strategy for building business resilience. Accurate inventory records prevent financial discrepancies, empower better decisions, and reduce unnecessary costs. Whether you’re running a retail chain, a manufacturing unit, or a warehouse the right audit process can uncover hidden inefficiencies and unlock growth potential.
Don’t treat inventory audits as just a checkbox for compliance see them as an investment in transparency, efficiency, and trust.
If you’re starting your audit process or looking to upgrade your current practices, begin with a simple checklist, build consistency, and invest in the right technology. You’ll not only boost operational control but also build long-term credibility with your stakeholders.
Subscribe to our newsletter and stay updated.