- Follow On:
- [email protected]
- +918655715397
- Thane west, Maharashtra - 400604
Receiving a GST notice can make even a well-organised finance team reach for the calculator and sometimes the coffee.But a GST notice does not automatically mean that your business has committed an offence or that tax is immediately payable. The correct response depends on why the notice was issued, what period it covers, what information the department has considered, and what your records show.The first rule is simple: do not reply in a hurry. Check the notice, verify the facts, reconcile the data and then respond.
This guide explains what to do after receiving a GST notice, what businesses should check before replying, and how to avoid common GST notice response mistakes.
The first step is to identify exactly what communication you have received.
GST communications can relate to different matters, including return discrepancies, input tax credit, tax liability, registration, refunds or other compliance issues. The response mechanism and applicable timeline can vary depending on the type of proceeding.
Under the GST framework, notices and other communications may be served through several permitted channels, including making them available on the common portal.
When a GST notice is received on the GST portal, check:
Do not treat the deadline as a suggestion. A delayed response to a GST notice can create additional complications.
Before preparing a reply, understand the exact reason behind the notice.
Common issues may include:
For example, an ITC-related notice may require you to examine purchase invoices, books, GSTR-2B and other supporting records rather than simply writing that the ITC claim is correct.
The CGST framework specifically covers situations involving tax that was not paid or was short-paid, erroneous refunds, and wrongly availed or utilised input tax credit.
In short: understand the question before writing the answer.
This is where the real work begins.
Your GST notice verification checklist should start with the data mentioned in the notice. Compare the department’s observation with your GST returns, books and supporting documents.
For an ITC-related issue, perform GSTR-2B reconciliation with your purchase register and books.
GSTN advises taxpayers to reconcile GSTR-2B data with their own records and books of accounts. It also advises taxpayers to ensure that credit is not claimed twice and that applicable reversals are made in GSTR-3B.
Depending on the issue, check:
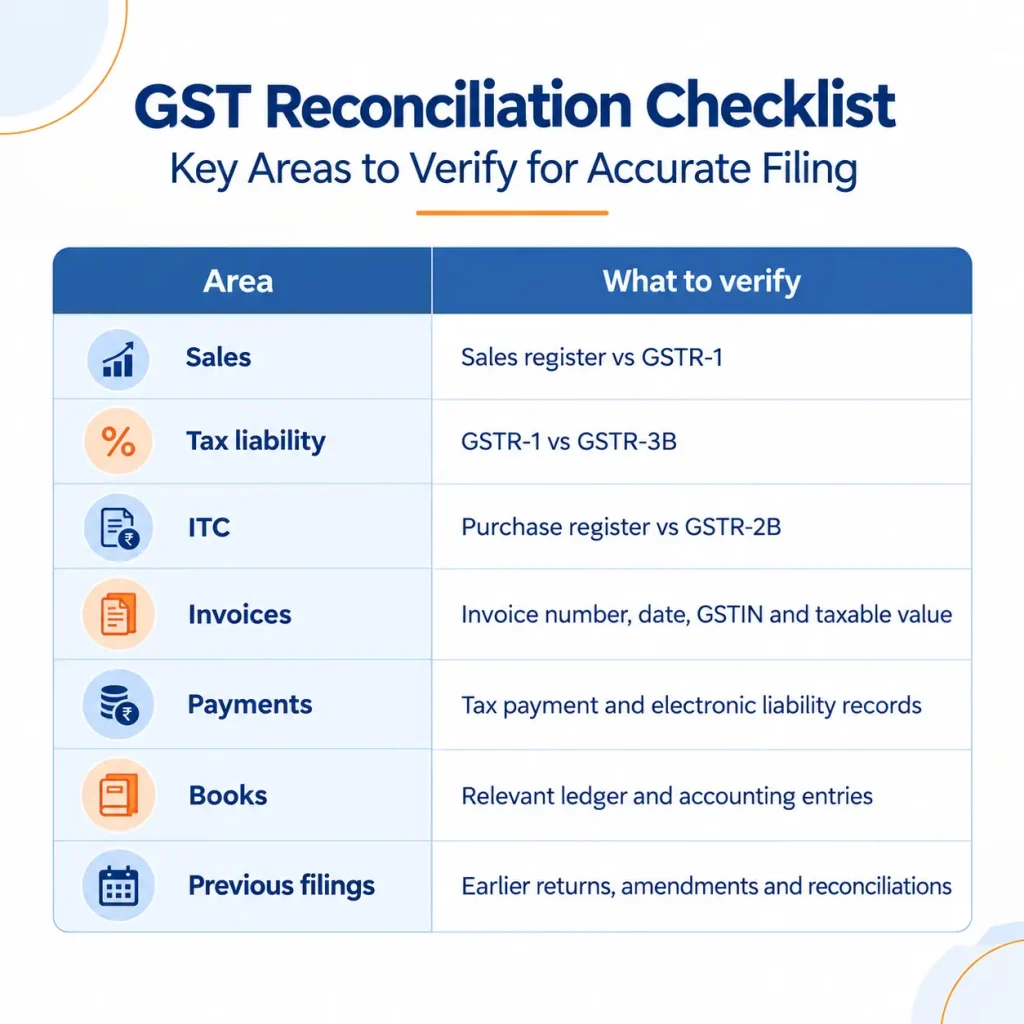
For older periods or specific reconciliation requirements, businesses may also need to examine GSTR-2A reconciliation alongside other records. The exact reconciliation should match the issue raised in the notice.
A reply without reconciliation can create more questions than it answers.
Suppose a notice says your ITC does not match the department’s data. Simply replying, “The ITC is correct as per our books” may not adequately address the discrepancy.
Instead, identify the difference.
For example:
Purchase register → GSTR-2B → GSTR-3B → invoices → accounting records
Then classify the difference. It could arise from timing, amendments, supplier reporting, data-entry issues, reversals or another documented reason.
GSTN’s GSTR-2B guidance specifically states that taxpayers should reconcile the statement with their records and books and ensure that ineligible credit is not claimed.
This makes the GST notice reconciliation process an important part of preparing a factual response.
Once you understand the discrepancy, prepare a structured response.
A useful GST notice reply format can include:
Keep the language factual and easy to follow.
Avoid emotional explanations, unnecessary background or unsupported statements. A tax response is not the place for creative writing.
If the business accepts part of the discrepancy, state the facts accurately and consider the applicable statutory procedure before making any payment or commitment.
For show-cause proceedings, GSTN lists FORM GST DRC-06 as the taxpayer’s reply to a Show Cause Notice. However, businesses should not assume that DRC-06 applies to every GST communication; the applicable form and online workflow depend on the nature of the notice.
Businesses asking how to reply to GST notice online should first identify the notice and its available response facility on the GST portal.
A typical process involves:
Log in → Locate the relevant notice/order → Review the notice → Select the applicable reply option → Enter the response → Upload supporting documents → Submit → Preserve the acknowledgement/reference.
GSTN has provided portal functionality for taxpayers to access additional notices and orders and, for applicable proceedings, submit responses and supporting documents electronically.
The exact steps can vary by notice type, so follow the response option displayed against the particular communication rather than using a generic GST notice response process.
The documents required to respond to a GST notice depend entirely on the issue raised.
For an ITC mismatch, supporting records may include relevant:
For a sales mismatch, the relevant evidence may instead involve sales registers, invoices, GSTR-1, GSTR-3B and related records.
Do not upload documents simply because you have them. Every attachment should support a specific statement in your response.
This also helps prevent GST notice documentation mistakes, such as missing evidence, inconsistent figures or unclear supporting files.
Several mistakes can weaken an otherwise valid response.
Before submitting your response, ask:
A few minutes of checking can prevent hours of avoidable back-and-forth.
The consequences depend on the type of notice and the applicable legal provision. Ignoring a notice can prevent the taxpayer from presenting its explanation or supporting evidence within the prescribed process.
For example, under the CGST Act, certain proceedings provide the taxpayer an opportunity to make a representation before the proper officer determines the amount payable.
Therefore, businesses should not assume that silence will resolve the issue.
If the notice involves significant tax exposure, complex ITC issues, repeated discrepancies, allegations of fraud or suppression, or a matter requiring detailed legal interpretation, professional tax advice may be appropriate.
A GST notice received what to do situation becomes much easier when businesses follow a structured process.
First, verify the notice. Then understand the issue, reconcile the relevant records, collect supporting documents and prepare a clear response. Finally, submit it through the applicable GST portal workflow within the prescribed timeline.
The goal is not to write the longest reply. It is to provide a clear, accurate and properly supported response to the issue raised.
For businesses, strong GST compliance starts long before a notice arrives. Regular reconciliation, accurate records and timely return reviews can help identify discrepancies before they become bigger problems.
First, verify the notice number, date, tax period, reason for the notice and response deadline. Then review the relevant GST returns, books and supporting documents before preparing a response.
Log in to the GST portal, locate the relevant notice or proceeding, review the available response option, provide your explanation, upload supporting documents and submit the response. The exact workflow depends on the type of notice.
The response timeline depends on the type of notice and the applicable provision. Businesses should always follow the specific deadline mentioned in the notice rather than relying on a general timeline.
Documents depend on the issue raised. They may include GST returns, invoices, purchase or sales registers, GSTR-2B, books of accounts, reconciliation statements and other records relevant to the discrepancy.
GSTR-2B reconciliation helps businesses compare eligible input tax credit with their purchase records and books. It can help identify differences that need explanation before responding to an ITC-related notice.
Yes. Differences involving input tax credit can result in GST-related communications or proceedings. Businesses should investigate the underlying records and reconcile the relevant data before responding.
Common mistakes include missing the deadline, submitting an incorrect response, failing to reconcile figures, providing incomplete documents, using a generic reply and not addressing each issue raised in the notice.
The consequences depend on the type of notice and applicable legal provisions. Failing to respond can mean that the taxpayer misses the opportunity to present relevant explanations or supporting evidence within the prescribed process.
A basic structure can help organise a response, but businesses should not rely on a generic format. The reply should address the specific notice, tax period, discrepancy, facts and supporting documents.
Professional assistance can be useful when the notice involves significant tax exposure, complex ITC reconciliation, repeated discrepancies, multiple GST periods, or issues requiring detailed tax or legal interpretation.
Need support with GST reconciliation, notice response or ongoing GST compliance? Wisecor can help businesses review GST records, reconcile discrepancies and manage compliance processes with a structured approach.
Subscribe to our newsletter and stay updated.