- Follow On:
- [email protected]
- +918655715397
- Thane west, Maharashtra - 400604
Not every rupee you receive is taxable. Indian tax law keeps certain receipts outside your taxable income, from farm earnings and family gifts to provident fund payouts and retirement benefits.
Since 1 April 2026, the Income-tax Act, 2025 has applied to income earned in the new “Tax Year”, replacing the Income-tax Act, 1961 for that period. The list of exempt incomes has been reorganised, but the main exemptions taxpayers rely on continue. Below are eight types of income that are generally tax-free, along with the conditions attached to each.
Two points first:
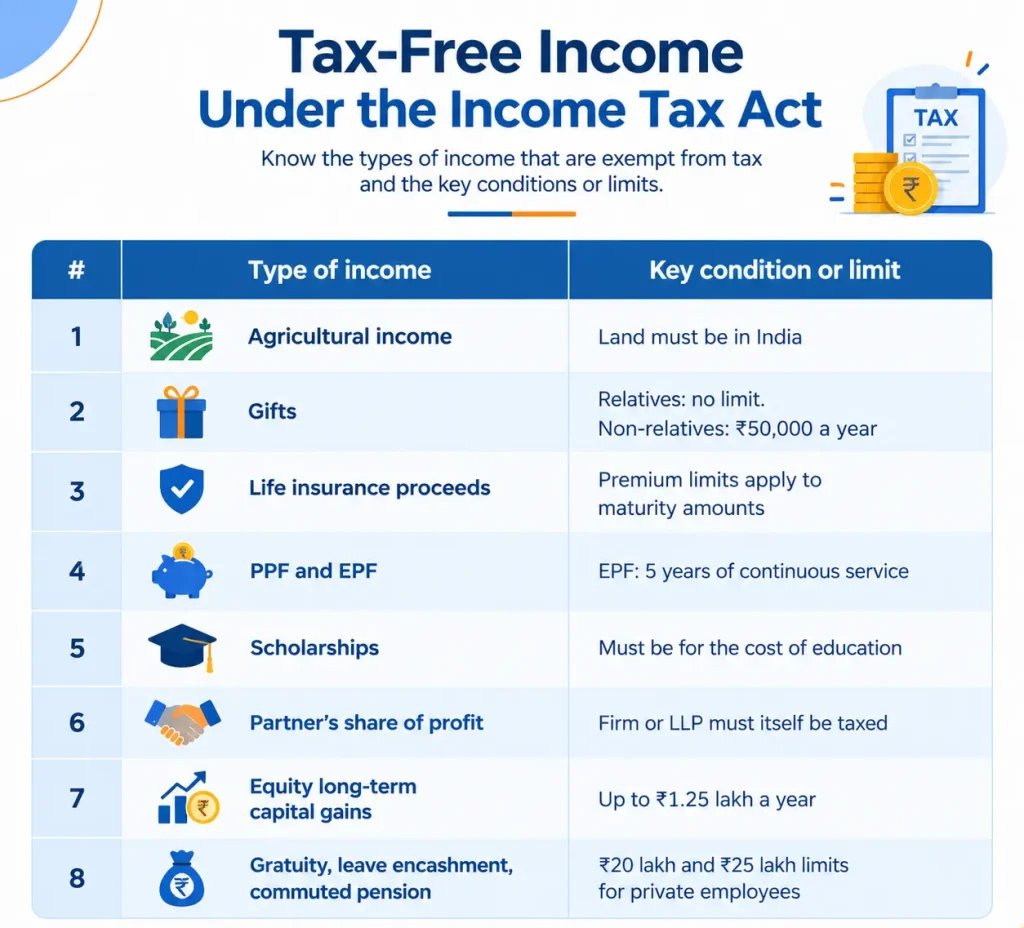
Income from agricultural land situated in India is exempt from income tax. This covers revenue from cultivating crops and rent received from land used for agricultural purposes. Income from agricultural land outside India is not covered.
In some cases, exempt agricultural income can still affect your tax bill. If your net agricultural income is above ₹5,000 and your other income is above the basic exemption limit, the agricultural income may be taken into account to work out the rate of tax on your non-agricultural income. This is known as partial integration.
Why it matters: Farmers and landowners should keep land records and proof of crop sales or rent, and disclose the income correctly in their return.
Gifts from specified relatives, such as a spouse, parents and siblings, are tax-free regardless of the amount. Gifts received on the occasion of your marriage, and property received through a will or inheritance, are also not taxed as income.
Gifts from non-relatives are treated differently. If the total received in a year exceeds ₹50,000, the entire amount becomes taxable, not just the excess. Under the Income-tax Act, 2025, these rules sit in Section 92, which replaces the earlier Section 56(2)(x).
The income a gifted asset earns later, such as interest or rent, is taxable in the recipient’s hands like any other income.
Why it matters: The relationship between donor and recipient decides the tax treatment. Keep gift deeds, bank records and valuation documents for larger gifts.
The amount paid to a nominee on the death of the insured is tax-free. Maturity proceeds are also exempt, but only if the policy meets these conditions:
Why it matters: Policyholders with high-premium or multiple policies should check these limits before maturity, not after.
PPF: Interest on a Public Provident Fund account and the maturity amount are tax-free. The annual deposit limit is ₹1.5 lakh.
EPF: A withdrawal is tax-free if you have completed five years of continuous service. This includes earlier jobs, provided your PF was transferred rather than withdrawn. If you withdraw earlier, parts of the amount can become taxable, and TDS may apply on taxable withdrawals of ₹50,000 or more.
Interest earned on your own contributions above ₹2.5 lakh in a year is taxable. A higher ₹5 lakh limit applies where there is no employer contribution.
Why it matters: Employees changing jobs should transfer their PF instead of withdrawing it. Higher earners with large VPF contributions should track the ₹2.5 lakh threshold.
Scholarships granted to meet the cost of education are exempt. The exemption depends on the purpose of the money rather than a fixed rupee cap. Certain cash awards instituted by the Central or State Government in the public interest are also exempt, subject to the conditions notified.
Why it matters: Keep the sanction letter and proof that the amount was for education. Payments for services rendered, such as some stipends, may be treated differently.
A partner’s share in the profits of a firm or LLP is exempt in the partner’s hands, because the firm or LLP itself pays tax on its income.
Salary, bonus, commission or interest paid to partners, within the limits allowed by law, is taxable as business income of the partner.
Why it matters: For business owners, how remuneration and profit share are structured in the partnership deed affects the partners’ tax outgo.
Long-term capital gains on listed equity shares and equity-oriented mutual funds (held for more than 12 months) are exempt up to ₹1.25 lakh in a year. Gains above that are taxed at 12.5% without indexation.
The limit is a combined annual figure across all eligible equity gains, not a separate limit for each investment.
Why it matters: Investors can plan redemptions across years to use the exemption. The rebate that makes income up to ₹12 lakh tax-free does not apply to income taxed at special rates, such as these gains.
These benefits remain available under the new tax regime.
Why it matters: Employees nearing retirement and the payroll teams processing their payouts should calculate the exempt and taxable portions before the final settlement.
A new law, a new structure. The Income-tax Act, 2025 applies from 1 April 2026. The long list of exemptions in Section 10 of the 1961 Act now sits in Section 11, read with Schedules II to VII. For example, life insurance receipts are in Schedule II. The change is largely structural, and the limits discussed above continue to apply.
Two laws apply at the same time. Income earned in FY 2025-26 (assessment year 2026-27) is still assessed under the 1961 Act, including the returns filed this year. Income from FY 2026-27 onwards falls under the 2025 Act as “Tax Year 2026-27”.
No change in slabs. Budget 2026 did not change the new regime’s slabs. Income up to ₹12 lakh results in zero tax through the rebate, which works out to ₹12.75 lakh for salaried taxpayers after the ₹75,000 standard deduction. This is a rebate, not an exemption, so it is different from the tax-free incomes above.
Employers and HR teams should ensure retirement-related payouts are computed within applicable limits and documented properly, so employees are not over- or under-taxed.
Several types of income are legally tax-free in India, but each comes with conditions. The limits that decide whether you pay tax are:
With two tax laws applying across FY 2025-26 and FY 2026-27, good record-keeping and correct reporting matter more than before.
This article is for general information. For advice on your specific situation, speak to a qualified tax professional or contact Wisecor’s tax and compliance team.
Subscribe to our newsletter and stay updated.