- Follow On:
- [email protected]
- +918655715397
- Thane west, Maharashtra - 400604
Businesses often hear the terms internal audit and statutory audit together, but they serve different purposes. While both involve reviewing financial information, controls and business processes, their objectives, scope and reporting requirements are not the same.
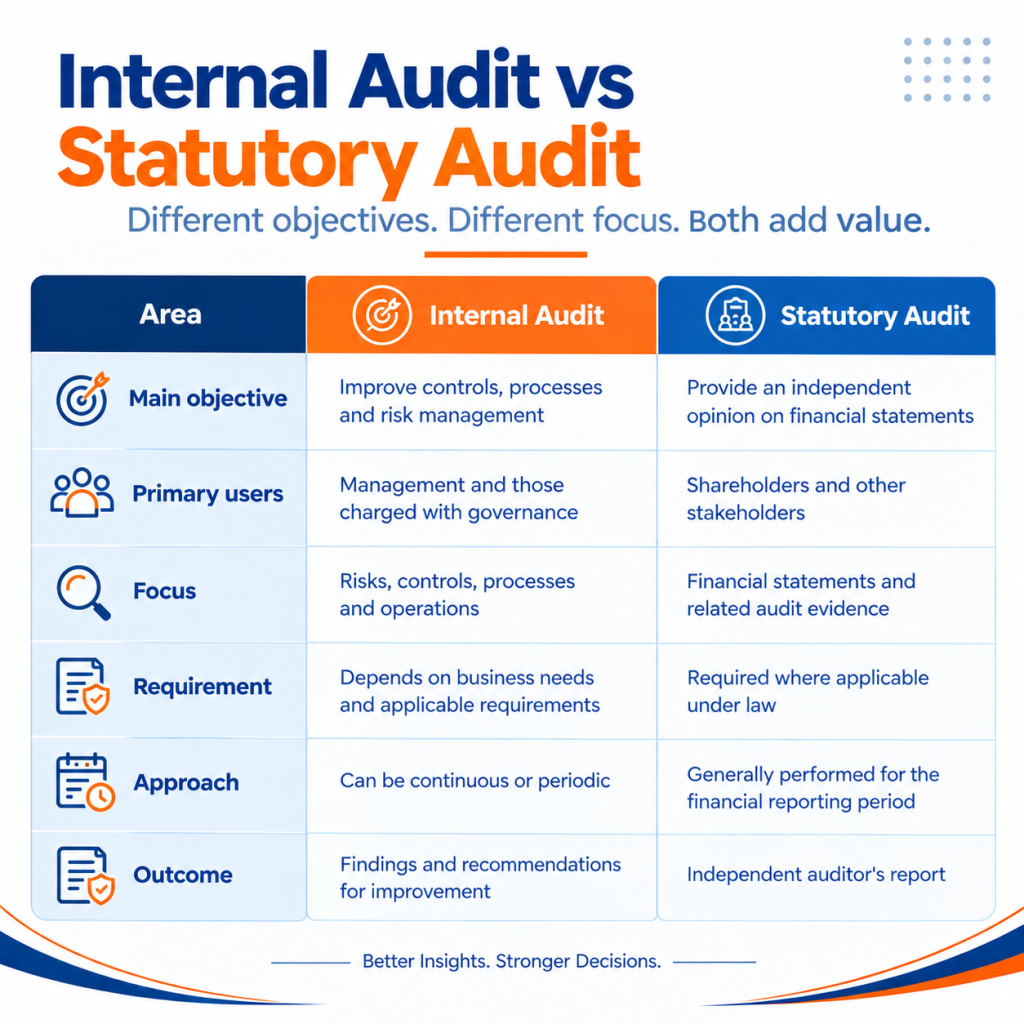
Understanding internal audit vs statutory audit is important for businesses that want stronger financial controls, better compliance and greater confidence in their financial reporting. A statutory audit may be required by law, while an internal audit is generally focused on helping management identify risks, improve processes and strengthen internal controls.
For growing businesses, the question is not always whether one can replace the other. In many situations, internal audit and statutory audit can work together to provide a more complete view of the organization’s financial and operational health.
An internal audit is an independent review of a company’s internal processes, controls, risks and operations. Its primary purpose is to help management understand whether business processes are working effectively and where improvements may be required.
Unlike a statutory audit, an internal audit is generally designed around the organization’s specific risks and management objectives. It can examine areas such as finance, procurement, payroll, inventory, revenue, compliance, information systems and operational controls.
For example, an internal audit may identify that:
The value of an internal audit goes beyond identifying errors. It can help management understand why a problem occurred and how the underlying process can be improved.
A statutory audit is an audit required under applicable law for eligible entities. Its primary purpose is to provide an independent opinion on whether the company’s financial statements present a true and fair view, in accordance with the applicable financial reporting framework.
A statutory audit generally focuses on financial statements, accounting records, supporting evidence and relevant financial reporting requirements.
The statutory auditor independently examines areas such as:
The outcome is an independent auditor’s report that provides assurance to stakeholders about the financial statements.
The simplest way to understand internal audit vs statutory audit is to look at their purpose.
Internal audit asks:
“How can the business improve its controls, processes and risk management?”
Statutory audit asks:
“Do the financial statements meet the applicable reporting requirements and present a true and fair view?”
No. Internal audit cannot replace statutory audit where a statutory audit is legally required.
The two audits have different objectives. Internal audit primarily supports management by reviewing business processes, internal controls, risk management and operational effectiveness. Statutory audit, on the other hand, provides an independent opinion on the company’s financial statements as required under applicable law.
For example, an internal audit may identify weaknesses in purchase approvals or inventory management and recommend corrective action. A statutory audit is primarily concerned with obtaining sufficient appropriate evidence to form an opinion on the financial statements.
Therefore, businesses should view internal audit vs statutory audit as complementary functions rather than alternatives.
Not every business needs the same level of internal audit activity. The requirement for a statutory audit depends on the applicable legal and regulatory framework, while the need for internal audit often increases with business complexity, size and risk exposure.
A growing company may benefit from internal audit when it has:
Even when a business has a relatively small finance team, an independent review of important processes can help management discover control gaps before they become expensive problems.
Risk management is one of the major areas where internal audit can provide value beyond financial statement review.
An internal auditor can evaluate whether important business risks have been identified and whether appropriate controls are actually operating. The review may cover financial, operational, compliance, technology and process-related risks.
For instance, if several employees can create vendors and approve payments without adequate segregation of duties, the organization may face a higher risk of unauthorized transactions.
An internal audit can bring such weaknesses to management’s attention and recommend practical controls.
The process generally involves:
Identify → Assess → Test → Report → Correct → Monitor
This makes internal audit particularly useful for businesses that want to move from reactive problem-solving toward proactive risk management.
The scope depends on the company’s objectives and risk profile. Unlike a statutory audit, an internal audit can be customized around specific business processes.
Common areas include:
The auditor may examine transactions, documents, system records and control procedures and then report identified gaps to management.
This flexibility is one of the key differences when comparing internal audit vs statutory audit.
Yes. Although internal audit is commonly associated with controls and compliance, it can also identify inefficient processes.
For example, an audit may reveal that the same financial information is entered manually into multiple systems. This creates unnecessary work and increases the possibility of errors.
The recommendation could involve:
For businesses considering finance and accounting outsourcing or automation, internal audit findings can also help identify processes that are suitable for redesign or technology-based improvement.
Outsourcing can be useful when a business wants an independent internal audit perspective without building a large permanent audit team.
An outsourced internal audit provider can bring specialized expertise and conduct reviews based on the organization’s risk areas and business objectives.
This model can be particularly practical for SMEs and growing companies that need stronger controls but may not require a full-time internal audit department.
Before selecting an internal audit services provider, businesses should evaluate:
The goal should not simply be to produce an audit report. A useful internal audit should help management understand the problem, prioritize the risk and take corrective action.
Internal audit focuses on improving controls, processes and risk management, while statutory audit provides an independent opinion on financial statements where legally required.
No. It depends on the business structure, applicable laws, financial thresholds and regulatory requirements.
It is mandatory for certain companies meeting prescribed criteria. Applicability depends on the company’s type and applicable legal requirements.
It depends on applicable laws, professional requirements and auditor independence rules. Potential conflicts of interest must be considered.
It depends on the business’s risk level. Internal audits may be conducted monthly, quarterly, half-yearly or annually based on specific requirements.
The auditor reports findings and recommendations. Management then takes corrective action, assigns responsibilities and may conduct follow-up reviews.
No. It can cover finance, payroll, procurement, inventory, compliance, technology, operations and internal controls.
Keep financial records, policies and supporting documents organized. Businesses should also review key controls, approvals, reconciliations and risk areas before the audit
For many growing organizations, the answer can be yes—because the two audits solve different problems.
A statutory audit provides independent assurance regarding financial statements where legally required. An internal audit gives management a broader opportunity to identify weaknesses in processes, controls and risk management.
Think of it this way:
Statutory Audit → Financial Reporting Assurance
Internal Audit → Controls, Risk & Process Improvement
Using both approaches can give businesses greater visibility into not only whether the financial information is reliable, but also whether the processes producing that information are working effectively.
For companies experiencing rapid growth, expanding operations, increasing transaction volumes or managing multiple locations, this distinction becomes particularly important.
A well-planned audit approach should go beyond finding mistakes after they happen. It should help businesses identify risks early, improve controls, strengthen financial processes and support better decision-making.
Wisecor can support businesses with internal audit, finance and accounting, compliance, process improvement and related business support services, helping management build more structured and control-focused operations.
Looking to strengthen your internal controls and audit readiness? Connect with Wisecor to discuss your business requirements.
Subscribe to our newsletter and stay updated.