- Follow On:
- [email protected]
- +918655715397
- Thane west, Maharashtra - 400604
Tax Deducted at Source (TDS) is one of those things that looks simple until it isn’t. You pay a vendor, deduct a slice, deposit it, file a return, and somehow still end up with a notice. This guide covers the TDS section-wise rates, due dates, penalties, and the mistakes that cost businesses the most.
Quick note: From 1 April 2026, the Income-tax Act, 2025 replaces the 1961 Act. TDS provisions now sit under Section 393, but the older section numbers such as 194C and 194J are still widely used for reference. Always check the current rate chart on the before you deduct.
TDS means the payer deducts tax at the time of making a payment, then deposits it with the government. The aim is simple: collect tax at the source of income rather than chasing it later. Think of it as the government asking for its share upfront, before the money leaves your hands.
If you’re a business that makes payments for services, rent, commission, or interest, TDS applies to you. Miss the deduction or deposit, and the interest and penalties add up quickly.
The rates below reflect the commonly applied rates for FY 2026-27 as reported by Thresholds can change, so treat them as a starting point.
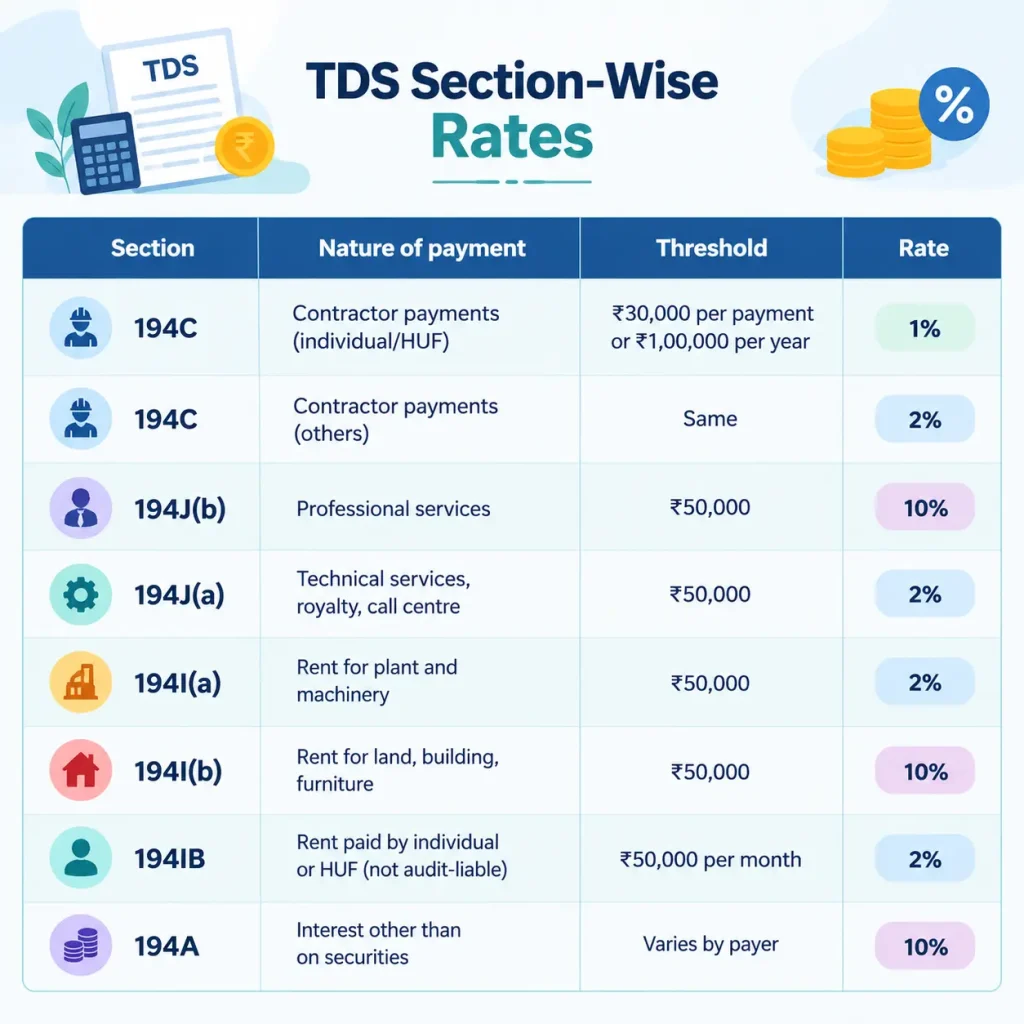
Section 194H covers commission and brokerage, and its rate and threshold have changed in recent updates. Confirm the current figure in the official chart before deducting.
Salary falls under Section 192, which uses your employees’ income tax slab rates, not a flat percentage.
Most businesses mix up two dates: the deposit date and the return date. They’re different.
Deposit TDS by the 7th of the following month. For example, tax deducted in June must reach the government by 7 July. Set a reminder around the 5th so you have a buffer.
TDS deducted in March has a later deadline: 30 April. Most compliance calendars, including report this date. Mark it clearly, because March is the month most people forget.
You file TDS returns every quarter. For FY 2026-27, the due dates are:
The return reports what you have already deposited. Filing on time doesn’t cure a late deposit, so keep both deadlines on your calendar.
After filing your return, you must issue TDS certificates to the people you deducted from:
Both are generally due within 15 days of the return due date. For example, Q2 certificates follow the 31 October return, so they’re due by 15 November.
Returns are filed in the form that matches the payment type. Salary returns use Form 24Q, resident non-salary returns use Form 26Q, and payments to non-residents use Form 27Q. Under the 2025 Act, forms have been renumbered, so check the current form numbers on the portal before filing.
Late TDS costs more than most people expect. Here’s how it works:
So, what happens if TDS is deposited late? Interest starts immediately, and it accumulates for every month or part of a month. A delay of a few days still counts as a full month, which makes early payment a smart habit.
Most TDS problems come from a handful of repeat mistakes:
Wrong PAN. If the deductee hasn’t provided a valid PAN, you may need to deduct at a higher rate under Section 206AA. A typo in PAN can also cause mismatches in the return and the deductee’s Form 26AS.
Wrong section. Choosing 194J when the payment falls under 194C changes both the rate and the threshold. Read the nature of the service before you pick a section.
Short deduction of TDS. Deducting less than the required amount leaves you liable for the shortfall, plus interest. This is a classic mistake when people deduct TDS on the amount net of GST, when the rules call for the full amount.
Mismatched challan details. A challan with the wrong TAN, amount, or section won’t match the return, and the deductee’s credit may not appear. Always quote your TAN on every challan and return.
Late or missing certificates. Employees and vendors can’t claim credit without Form 16 or 16A, which creates friction and questions.
Two sections often surprise businesses:
Checking the vendor’s PAN and tax-filing status before the first payment saves a lot of trouble later.
Every person who deducts TDS needs a Tax Deduction and Collection Account Number (TAN). You quote it on challans, returns, and certificates. Apply for it through the official portal before your first deduction.
If you expect your tax liability on a payment to be lower than the standard TDS, you can apply for a lower or nil deduction certificate under Section 197. In the 1961 framework, this application used Form 13. Check the current form on the Income Tax portal before applying.
Is TDS deducted on GST-inclusive invoices?
Generally, TDS applies to the amount excluding GST when the invoice separates the two. Confirm the treatment for your specific case with your accountant.
Can I deposit TDS through the e-Pay Tax section?
Yes. Use the e-Pay Tax option on the and select Challan 281.
What if I deducted TDS but forgot to file the return?
File it as soon as possible. Late filing triggers the Section 234E fee and possible penalties, so act quickly.
TDS compliance rewards consistency. Keep a monthly deposit calendar, verify PANs before every payment, and file returns a few days early. A disciplined process costs far less than fixing mistakes after a notice arrives.
Need help setting up your TDS calendar or reviewing past returns? for support with your compliance workflow.
Subscribe to our newsletter and stay updated.